Lennar Corporation reported third-quarter 2026 net earnings attributable to the company of $284 million, or $1.19 per diluted share, down from $591 million, or $2.29 per diluted share, a year earlier, according to the company's earnings release. The homebuilder also lowered its full-year 2026 delivery target to approximately 80,000 to 81,000 homes, down from the 82,000 to 83,000 homes it had discussed a quarter earlier, citing continued pressure on interest rates and deteriorating market conditions through the quarter.
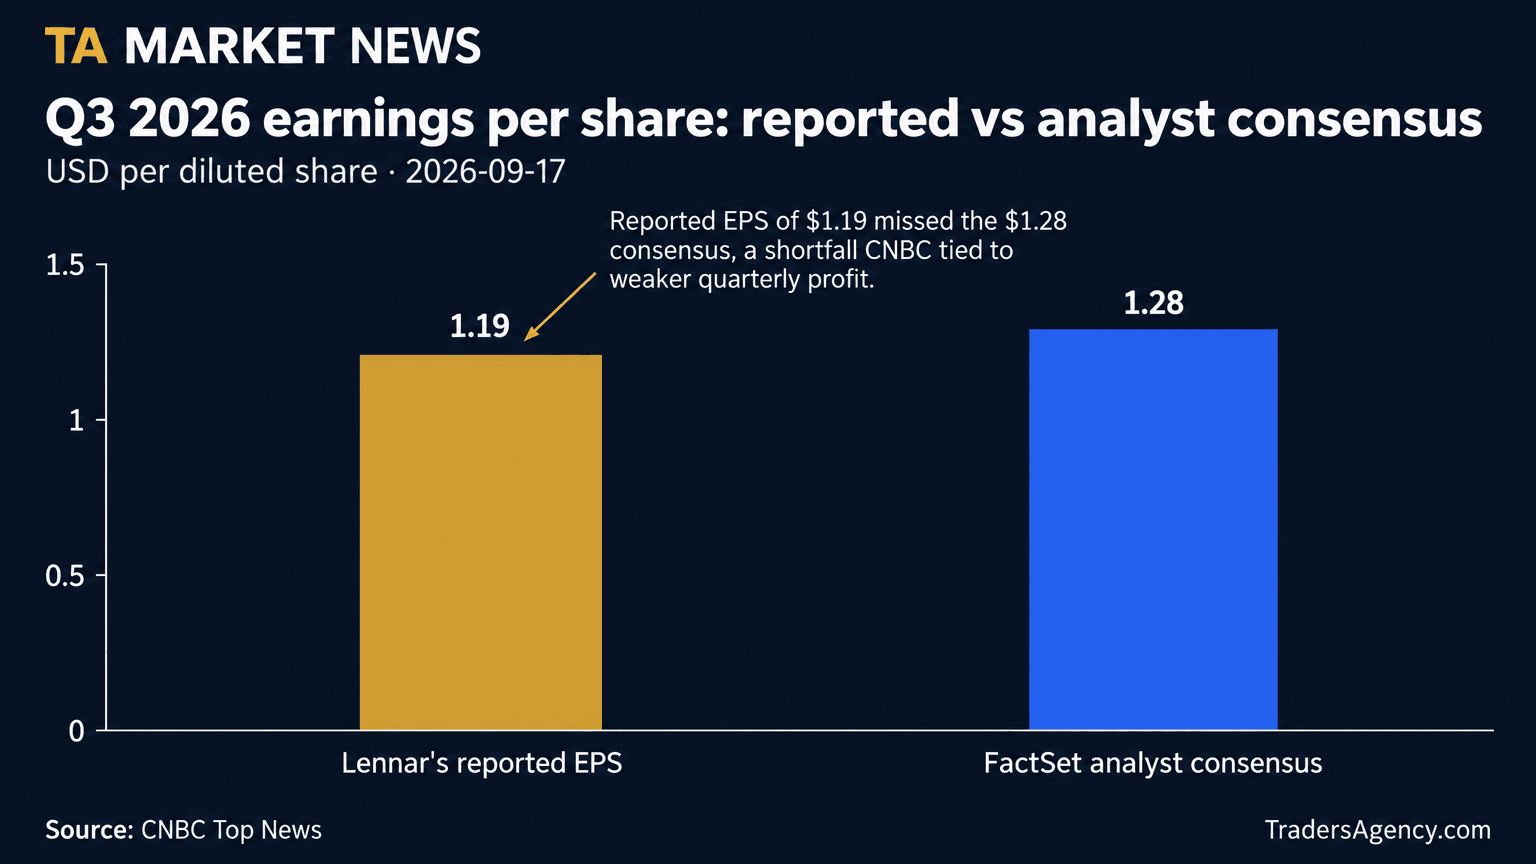
The results were released after the market close on September 16, 2026, according to Yahoo Finance, with a conference call to discuss them held at 11:00 a.m. Eastern Time the following day, per the company's earnings release. The quarter missed Wall Street expectations. Per CNBC, Lennar's reported $1.19 per share fell short of the $1.28 a share analysts polled by FactSet had expected, a shortfall of $0.09, or roughly 7% below consensus by our calculation (1.19 minus 1.28, divided by 1.28). Revenue came in at $8.05 billion versus an $8.23 billion consensus estimate, a gap of $0.18 billion, or about 2.2% below expectations by the same method (8.05 minus 8.23, divided by 8.23).
What Drove the Earnings Decline
Excluding $53 million of mark-to-market losses on technology investments and $39 million, net, of one-time items in its Financial Services segment, Lennar said adjusted third-quarter net earnings were $294 million, or $1.23 per diluted share, compared with $516 million, or $2.00 per share on a comparable basis, a year earlier when the company recorded mark-to-market gains of $99 million on technology investments, according to the company's release.
Executive Chairman and CEO Stuart Miller said the average sales price of $372,000 in the quarter reflected approximately 12.0% in incentives, along with base price adjustments necessary to sustain volume in a market where affordability remains the defining constraint. He said gross margin improved sequentially to 15.8%, with SG&A of 9.2% resulting in a net margin of 6.6%, per the earnings release.
Miller said conditions had deteriorated since the company's prior earnings call, with the 30-year mortgage rate at approximately 6.8% at quarter end and even higher since, alongside declining consumer confidence. He described earnings of $1.19 per share as below expectations but reflective of the operating environment. Nine-month deliveries totaled 58,222 homes versus 59,549 a year earlier, with year-to-date earnings per share of $3.36 against $6.06 in the prior-year period, according to the release.
Fourth-Quarter Guidance
For the fourth quarter, Lennar guided to 19,500 to 20,500 new orders and 22,000 to 23,000 deliveries, with gross margin of approximately 15.5% to 16.0%. The company expects average sales price in a range of $370,000 to $380,000, SG&A improving toward 8.7% to 9.0%, and Financial Services operating earnings of $90 million to $95 million, according to the earnings release.
Miller framed the company's approach as a continuation of its existing strategy rather than a shift, saying Lennar's consistent strategy has been to meet demand at affordability and build supply rather than wait the market out, prioritizing volume to create needed supply at affordable prices while leveraging scale advantages to improve margins over time, per the release.
Operating Metrics: Starts Pace, Cycle Time and Inventory
Miller said starts pace and sales pace were both 4.1 homes per community per month across the company's 1,713 active communities, which he described as reflecting an even-flow balance that drives efficiency. Construction cost per square foot improved 1% sequentially, 6% year over year, and 14% since the fourth-quarter 2023 baseline, while cycle time reached a record low of 116 days, down from 121 days the prior quarter and 126 days a year earlier, according to the release.
The company said it reduced completed, unsold inventory to 1.8 homes per community from 2.1 the prior quarter, with inventory turn at 2.4 times. Of the approximately 488,000 homesites Lennar says it owns and controls, the company said it owns fewer than 2.5% on its balance sheet, per the earnings release.
Capital Returns and Balance Sheet
Lennar repurchased 3 million shares of common stock for $256 million at an average price of $85.49 during the quarter and redeemed $400 million of 5.25% senior notes due June 2026. The company ended the quarter with $1.2 billion in homebuilding cash, according to the earnings release.
Bottom Line
Lennar's reduced 2026 delivery outlook, paired with quarterly profit that CNBC described as nearly half the year-earlier level and with misses on both earnings per share and revenue against analyst consensus, points — in our interpretation of the disclosed figures — to affordability pressure and higher mortgage rates weighing on the builder's volume-first approach. Management's own commentary cites incentives of approximately 12.0% alongside an average sales price of $372,000, and fourth-quarter gross margin guidance of 15.5% to 16.0% that brackets the 15.8% reported for the third quarter, which we read as an expectation that the pricing environment Lennar described will persist through year-end rather than ease. Readers should treat the guidance ranges as management's own forward targets, not independent forecasts, and weigh them against the deteriorating conditions Lennar itself flagged for the quarter just completed.
DISCLAIMER: Traders Agency does not offer financial advice. The information provided is for educational purposes only and should not be considered financial advice. Traders Agency is not responsible for any financial losses or consequences resulting from the use of the information provided. Trading carries inherent risks and may not be suitable for all individuals. You are advised to conduct your own research and seek personalized advice before making any investment decisions, recognizing the potential risks and rewards involved.
- Yahoo Finance: Lennar Corporation to Broadcast Its Third Quarter 2026 Earnings Call on September 17, 2026 · accessed Sep 17, 2026
- CNBC Top News: Stocks making the biggest moves premarket: GNRC, LEN, NKE · accessed Sep 17, 2026
- Lennar: Lennar Reports Third Quarter 2026 Results · accessed Sep 17, 2026
See more from Traders Agency on Google
Make us a preferred source and our market analysis will appear more prominently in your Google Search, Top Stories, and AI results.
Add to Preferred Sources