Dave & Buster's reported a net loss of $12.5 million for its fiscal second quarter, reversing a year-earlier profit of $11.4 million, as comparable store sales fell 2.9% and total revenue slipped to $544.1 million, according to the company's second quarter fiscal 2026 results released via GlobeNewswire after the market close on Monday, September 14, 2026. The stock was among names CNBC flagged as making the biggest premarket moves the following morning, though the size of that move was not specified in the network's report.
Revenue Mix Shifted Away From Entertainment
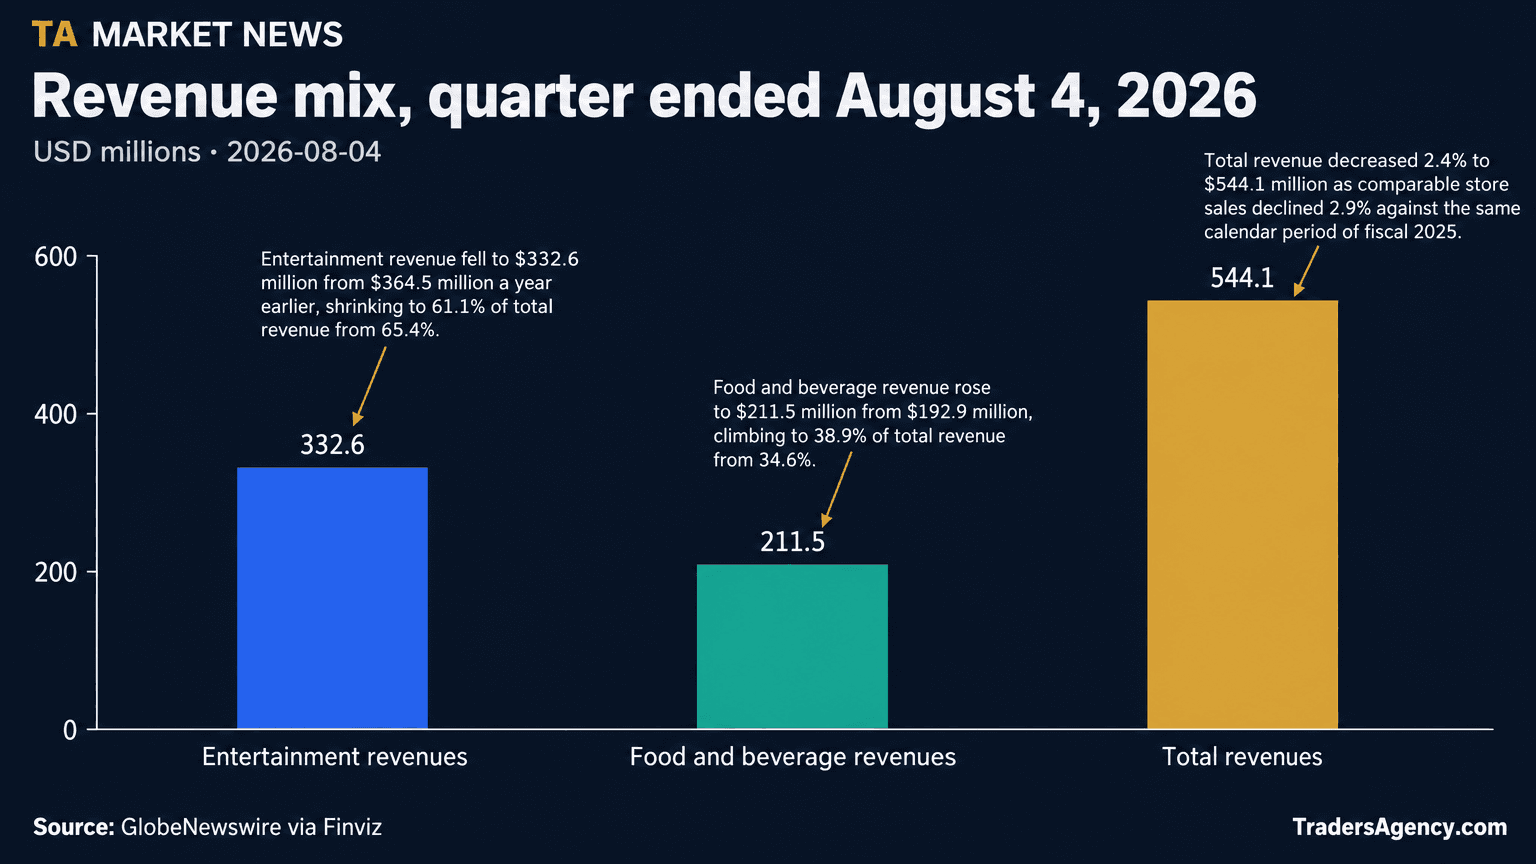
Total revenue declined 2.4% from $557.4 million a year earlier, according to the earnings release. The drop was concentrated in entertainment revenue, which fell to $332.6 million from $364.5 million and shrank to 61.1% of total revenue from 65.4%. Food and beverage revenue moved the other direction, rising to $211.5 million from $192.9 million and climbing to 38.9% of the total from 34.6%, the company reported. The release did not break out how much of the 2.9% comparable-sales decline came from entertainment versus food and beverage.
Margins Compressed Across the Business
Adjusted EBITDA fell to $98.9 million, or 18.2% of revenue, from $129.8 million, or 23.3% of revenue, in the second quarter of fiscal 2025, the company said. That represents a decline of 5.1 percentage points in adjusted EBITDA margin (our calculation: 23.3% minus 18.2%).
Operating income dropped even more sharply, to $19.4 million, or 3.6% of revenue, from $53.0 million, or 9.5% of revenue, a margin decline of 5.9 percentage points (our calculation: 9.5% minus 3.6%). Store operating income before depreciation and amortization, a non-GAAP measure, fell to $127.8 million, or 23.5% of revenue, from $155.4 million, or 27.9%, according to the release.
Fixed costs tied to the company's buildout added pressure. Depreciation and amortization rose to $73.7 million from $65.2 million, and pre-opening costs increased to $6.7 million from $4.1 million, the release showed. Net interest expense of $38.0 million exceeded operating income for the quarter, producing a pretax loss of $18.6 million that was partly offset by a $6.1 million income tax benefit, compared with pretax income of $14.3 million and a $2.9 million tax provision a year earlier.
The swing from net income to net loss totaled $23.9 million (our calculation: $12.5 million loss plus $11.4 million prior-year income). On an adjusted basis, the company reported an adjusted net loss of $9.5 million, or $0.27 per diluted share, versus adjusted net income of $14.2 million, or $0.40 per diluted share, a year earlier, a swing of $23.7 million (our calculation: $9.5 million plus $14.2 million).
Free Cash Flow Improved as Capital Spending Pulled Back
Away from the quarterly loss, the company pointed to improved cash generation over the first half of fiscal 2026. Adjusted free cash flow was positive $19.5 million for the six months ended August 4, 2026, compared with negative $36.5 million in the same period a year earlier, an improvement of $56.0 million (our calculation: $19.5 million minus negative $36.5 million). The company attributed the shift to lower capital expenditures of $190.0 million, down $53.8 million from $243.8 million a year earlier (our calculation), along with $48.9 million of sale-leaseback proceeds versus $73.0 million previously, according to the release.
Leverage Ratio at 3.5x, Debt Load Near $1.5 Billion
The company's credit-agreement metrics showed a Net Total Leverage Ratio of 3.5x, based on net debt of $1,543.3 million against trailing four-quarter Credit Adjusted EBITDA of $435.8 million, the release said. Net debt reflected total debt of $1,540.4 million, less $16.0 million of cash and cash equivalents and plus $18.9 million of outstanding letters of credit. Trailing four-quarter GAAP net loss was $88.7 million. The release did not disclose revolver availability or address any share-repurchase activity.
New Stores Continued to Open
Even as comparable sales declined, the store base kept expanding. Dave & Buster's operated 250 company-owned stores at quarter-end, up from 237 a year earlier, after opening six new domestic locations in the quarter, according to the release. Store operating weeks rose to 3,204 from 3,066. Looking ahead, the company said it expects to complete two additional Dave & Buster's remodels during the remainder of fiscal 2026, bringing the year's total to eight, and to open at least one more international franchise store beyond the six currently operating. No other forward guidance on capital expenditure levels or broader unit-growth targets was included in the release.
Management Points to a Turnaround Effort
New Chief Executive Officer Darin Harper framed the results around what the release called the company's "Back-to-Basics strategy," saying it is "gaining momentum with enhanced executional urgency." Harper said the company is "laser focused on returning to same-store sales and EBITDA growth, sharpening our margin management with cost saving initiatives, generating significant free cash flow, and delivering meaningful shareholder value," according to the release.
Harper also said comparable sales trends had begun to turn, noting "we improved overall same store sales in July, and saw continued improvement in overall same store sales during the third quarter to date." He pointed to "ongoing growth in food and beverage sales as well as in special events sales," and said remodeled stores "continue to outperform the system" on a same-store-sales basis, per the release. The release did not provide specific percentage figures for the July or third-quarter-to-date trends, nor did it quantify how much of the improvement came from food and beverage versus entertainment spending.
Market Reaction
CNBC listed Dave & Buster's among the stocks making the biggest premarket moves on Tuesday, September 15, 2026, in a roundup that also included Enova and Etsy. CNBC's report did not specify the magnitude of the premarket move or cite any sell-side analyst rating or estimate changes tied to the earnings release.
Bottom Line
Dave & Buster's second-quarter results show a company whose entertainment-driven revenue base is shrinking even as food and beverage sales grow, producing a GAAP net loss, a wider adjusted loss, and compressed margins across operating income and EBITDA. At the same time, lower capital expenditures and sale-leaseback proceeds pushed adjusted free cash flow positive for the first half of the fiscal year, and the Net Total Leverage Ratio stood at 3.5 times credit-adjusted EBITDA as defined in the company's credit agreement. Management's own commentary points to sequential improvement in same-store sales entering the third quarter, but the company has not yet quantified that recovery or laid out capital-spending or unit-growth targets beyond a handful of planned remodels and one additional international franchise store.
DISCLAIMER: Traders Agency does not offer financial advice. The information provided is for educational purposes only and should not be considered financial advice. Traders Agency is not responsible for any financial losses or consequences resulting from the use of the information provided. Trading carries inherent risks and may not be suitable for all individuals. You are advised to conduct your own research and seek personalized advice before making any investment decisions, recognizing the potential risks and rewards involved.
See more from Traders Agency on Google
Make us a preferred source and our market analysis will appear more prominently in your Google Search, Top Stories, and AI results.
Add to Preferred Sources