DICK'S Sporting Goods reported second-quarter results showing solid growth in its core namesake business alongside a sharp profit decline tied to the Foot Locker acquisition, prompting the company to lower its full-year 2026 earnings guidance. The DICK'S Business posted 4.9% comparable sales growth, but consolidated earnings fell year over year and management pointed to an increasingly promotional footwear and apparel market that hit Foot Locker's legacy-heavy assortment particularly hard.
Second-Quarter Results Fall Short of Estimates
DICK'S reported net income of $315.5 million, or $3.50 per diluted share, down from $381.4 million, or $4.71 per diluted share, a year earlier, according to the company's earnings release. Non-GAAP earnings per diluted share were $3.53, compared with $4.38 in the prior-year quarter.
Those adjusted results missed Wall Street expectations. Per Zacks Investment Research, as reported by Yahoo Finance, adjusted earnings of $3.53 per share came in below the Zacks Consensus Estimate of $3.78, while revenue of $5.59 billion trailed the consensus estimate of $5.63 billion.
FY2026 Guidance Cut
DICK'S now expects full-year net sales of $21.9 billion to $22.2 billion, GAAP earnings per diluted share of $10.94 to $11.94, and GAAP operating income of $1.45 billion to $1.55 billion, according to the company's release. On a non-GAAP basis, that translates to earnings per share of $11.00 to $12.00, down from the prior range of $13.50 to $14.50, as reported by Yahoo Finance citing the company's updated outlook.
The reduction is substantial: the midpoint of the new non-GAAP range falls to $11.50 from $14.00 in the prior guidance, a cut of about $2.50 per share (14.00 - 11.50 = 2.50). Interpreting the company's own disclosures, that pressure appears concentrated in the Foot Locker Business rather than the core DICK'S banner — The Globe and Mail reported that margin pressure and earnings dilution from the acquisition led management to cut operating income and Foot Locker sales guidance for 2026 while leaving DICK'S comp targets intact.
Segment Divergence: DICK'S Gains, Foot Locker Loses
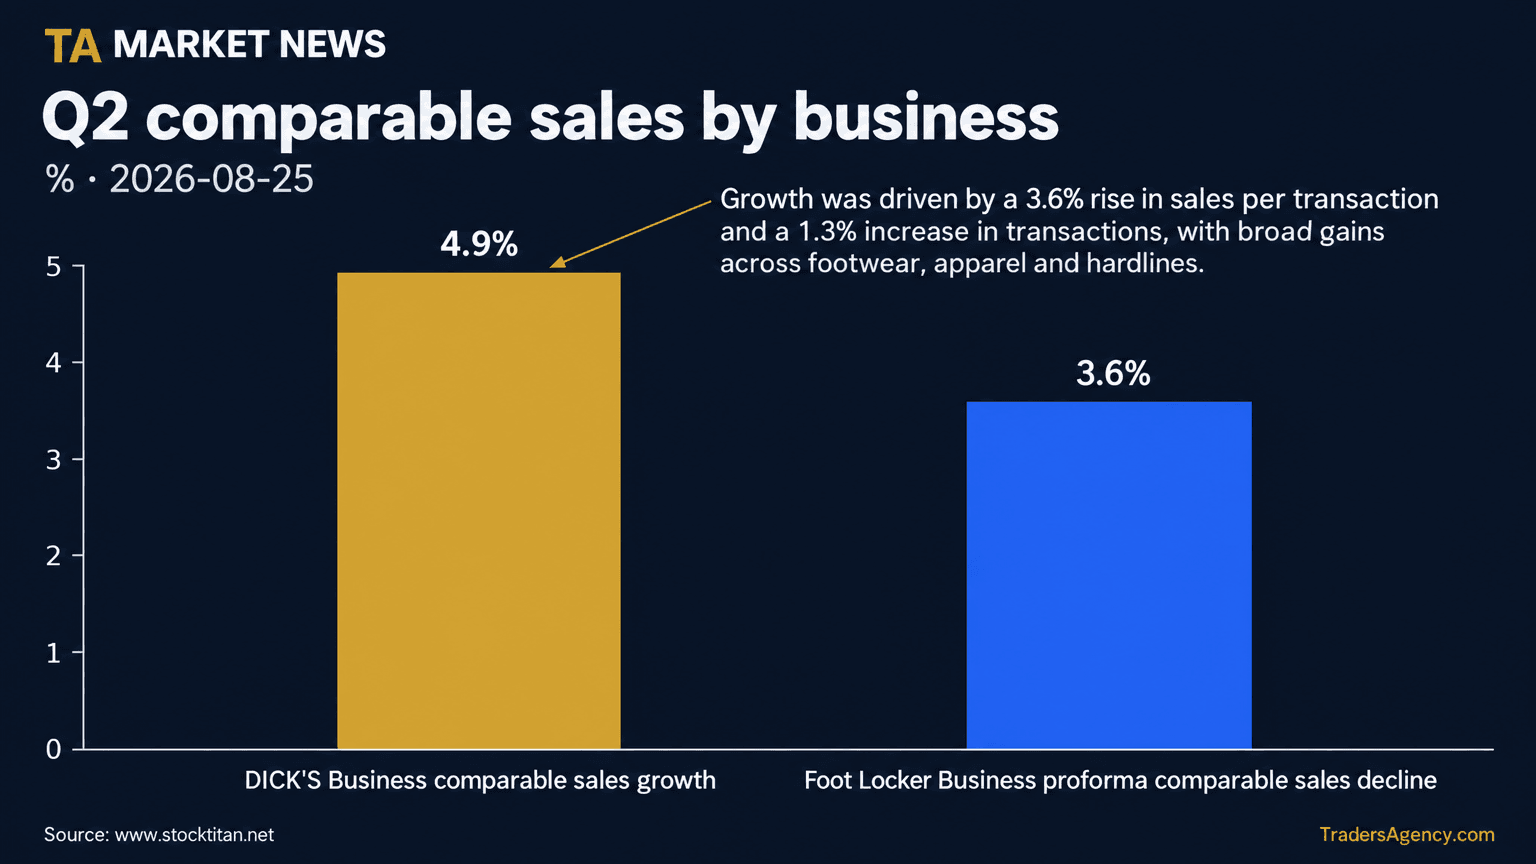
The two segments moved in opposite directions. The DICK'S Business generated segment profit of $485.2 million, up 2.2% from $475.0 million a year earlier, even as segment profit margin slipped 42 basis points, per the company's filing. Comparable sales growth of 4.9% for the DICK'S Business was driven by a 3.6% increase in sales per transaction and a 1.3% increase in transactions, with broad-based growth across footwear, apparel and hardlines, including strong results tied to the 2026 FIFA World Cup and trading cards, partially offset by declines in golf, outdoor equipment and accessories, the company said.
The Foot Locker Business, by contrast, posted a segment loss of $31.9 million on $1.7 billion of net sales for the quarter, and $14.4 million on $3.5 billion for the first half, according to the filing. Consolidated gross profit rose to $1,943.3 million from $1,351.3 million, but fell 228 basis points as a percentage of net sales, driven primarily by a 379-basis-point drag from lower gross margin in the Foot Locker Business. That was partially offset by a 79-basis-point gain in the DICK'S Business and a 68-basis-point, or $38.1 million, benefit from prior-year IEEPA tariff refunds, the company reported.
Because Foot Locker was only recently acquired, its comparable sales are currently reported on a proforma basis. Proforma comps for the Foot Locker Business declined 3.6% in the quarter, which the company said reflected challenging conditions in the athletic footwear marketplace — a contrast with the 4.9% comp gain at the DICK'S Business. The company also said Foot Locker will not be included in quarterly comparable sales until the fourth quarter of fiscal 2026, and in full-year comparable sales until fiscal 2027.
What Management Said
Executive Chairman Ed Stack attributed the pressure to conditions that became increasingly promotional across portions of the athletic footwear and apparel marketplace as the quarter progressed, prompting the company to adjust pricing to stay competitive. He said this environment had a more significant impact on the Foot Locker Business given its greater exposure to legacy footwear silhouettes and dependence on launch and retro product, adding that there were fewer launches in the quarter and that those launches performed below both industry and company expectations, according to the earnings release.
CEO Lauren Hobart said the DICK'S Business gained market share with its 4.9% comp growth and credited significant investment tied to the FIFA World Cup, while the company adopted a more cautious view of the balance of the year, per the release.
Balance Sheet and Capital Allocation
Consolidated inventories rose 63% year over year to $5,565 million, though the company said DICK'S Business inventory increased only 6% year over year; the total included $2.0 billion attributable to the Foot Locker Business, according to the filing. The board declared a quarterly dividend of $1.25 per share on August 24, 2026, payable September 25, 2026 to holders of record September 11, 2026. Year-to-date share repurchases totaled $141 million, down from $299 million a year earlier. Full-year capital expenditures are planned at approximately $1.6 billion gross and $1.4 billion net, split roughly $1.2 billion gross for the DICK'S Business and $0.4 billion gross for Foot Locker, according to the company's disclosures.
Stock Reaction and Peer Context
Per Zacks Investment Research, as reported by Yahoo Finance, DKS shares had lost 33.2% over the prior six months, compared with a 20.5% decline for its industry, and the stock carried a Zacks Rank #5 (Strong Sell) at the time of that report. The same report noted that NIKE's fiscal fourth-quarter 2026 wholesale revenues rose 4% year over year while NIKE Direct revenues fell 7%, and that Under Armour recently updated its fiscal 2027 revenue expectations amid what management described as a challenging consumer demand environment, while maintaining its full-year profitability outlook.
Bottom Line
DICK'S core banner continues to gain ground, with 4.9% comparable sales growth and a 79-basis-point gross margin improvement attributed to the DICK'S Business, even as its segment profit margin slipped 42 basis points and the broader footwear market turned more promotional. The Foot Locker Business, by contrast, posted a segment loss and drove a 379-basis-point drag on consolidated gross margin, alongside a substantial cut to full-year profit guidance. Reading those disclosures together, the open question for investors is whether the promotional pressure management described on legacy footwear silhouettes and launch product eases before Foot Locker's comparable sales are formally reported starting in the fourth quarter of fiscal 2026.
DISCLAIMER: Traders Agency does not offer financial advice. The information provided is for educational purposes only and should not be considered financial advice. Traders Agency is not responsible for any financial losses or consequences resulting from the use of the information provided. Trading carries inherent risks and may not be suitable for all individuals. You are advised to conduct your own research and seek personalized advice before making any investment decisions, recognizing the potential risks and rewards involved.
- PR Newswire: DICK'S Sporting Goods, Inc. Reports Second Quarter Results · accessed Sep 25, 2026
- finance.yahoo.com: DKS Cuts 2026 Profit Outlook as Foot Locker and Promotions Pressure · accessed Sep 25, 2026
- www.stocktitan.net: DICK'S sales jump 53% to $5.6B as profit slips · accessed Sep 25, 2026
- www.youtube.com: - YouTube · accessed Sep 25, 2026
- builtin.com: Dick's Sporting Goods Company Growth, Stability & Outlook · accessed Sep 25, 2026
- www.stocktitan.net: DICK'S Q2 sales jump 53%, profit margin shrinks · accessed Sep 25, 2026
- www.theglobeandmail.com: DICK’S Sporting Goods Cuts Outlook After Foot Locker Deal · accessed Sep 25, 2026
See more from Traders Agency on Google
Make us a preferred source and our market analysis will appear more prominently in your Google Search, Top Stories, and AI results.
Add to Preferred Sources