PepsiCo topped Wall Street's third-quarter targets as growth in Latin America Foods and Asia Pacific offset continued softness in its home market, the company reported on October 8. Alongside the beat, PepsiCo raised its full-year revenue outlook to roughly 6% growth while trimming its full-year core earnings-per-share growth target to a range of 2.5% to 3.5%, according to the company's third-quarter earnings release.
Quarterly results beat Street estimates
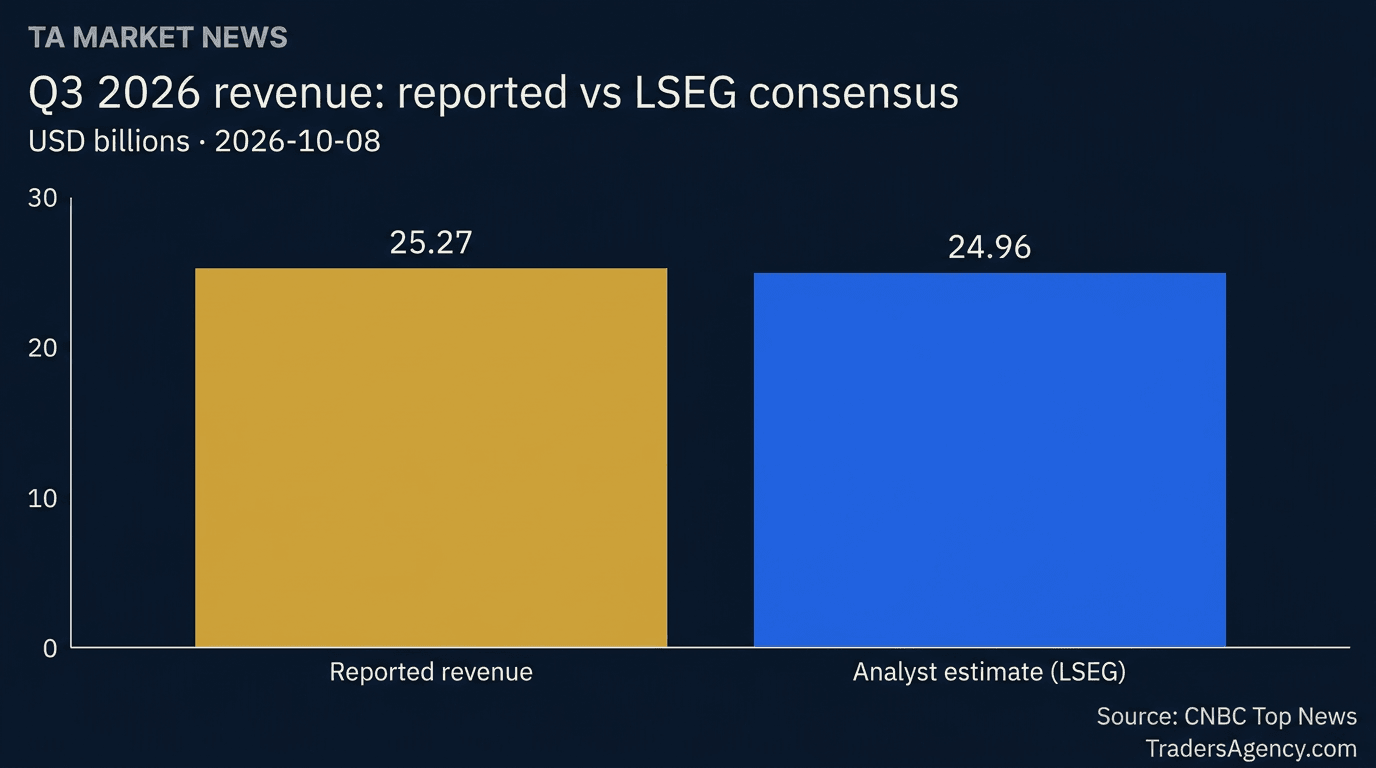
PepsiCo reported adjusted earnings of $2.34 per share on revenue of $25.27 billion for the quarter, both ahead of what Wall Street was expecting. Analysts surveyed by LSEG had forecast adjusted EPS of $2.29 and revenue of $24.96 billion, according to CNBC. That works out to a $0.05 beat on EPS, a 2.2% difference, and a $310 million beat on revenue, a 1.2% difference, based on our calculation using the reported and expected figures cited by CNBC.
Net sales rose 5.6% year over year to $25.27 billion, and organic revenue, which excludes acquisitions, divestitures and foreign exchange effects, increased 3.1% during the quarter, CNBC reported. Net income attributable to PepsiCo was $3.05 billion, or $2.23 per share, compared with $2.6 billion, or $1.90 per share, a year earlier, according to CNBC.
Guidance: revenue outlook up, core EPS growth target cut
For the full year, PepsiCo now expects revenue growth of about 6%, an increase from its prior outlook, while cutting its core EPS growth target to a range of 2.5% to 3.5%, per the company's earnings release. The guidance cut came as struggles in PepsiCo's home market weighed on profits with one quarter left in the fiscal year, CNBC reported.
International markets outshine North America
PepsiCo's international business accounted for 41% of the company's net revenue so far this year, CEO Ramon Laguarta said in prepared remarks reported by CNBC. The company saw volume growth in all but one of its international business units during the quarter; only its convenient foods division in Europe, the Middle East and Africa reported declining volume, down 1%. Separate Seeking Alpha coverage identified Latin America Foods and Asia Pacific as the units fueling that global momentum.
Companywide, beverage volume grew 3% and food volume grew 1%. But in North America, the picture was weaker: the beverage unit saw volume shrink 2%, while the North American food division reported flat volume, CNBC reported.
North America turnaround moving slower than planned
"Our business in North America performed below our expectations and represents a meaningful opportunity for improvement," Laguarta said in prepared remarks cited by CNBC. CFO Steve Schmitt said the turnaround of the domestic business is moving more slowly than expected.
Management did point to some pockets of sequential progress. The North American convenient foods business, which includes Doritos and Quaker Oats, saw organic revenue improve sequentially. The North American beverage unit, home to Pepsi-branded soda and Gatorade, saw organic volume trends pick up, helped by functional hydration and zero-sugar drinks. Even so, Pepsi's carbonated soft drink portfolio lagged the broader category, including rival Coca-Cola, according to CNBC's reporting.
Cost cuts and brand investment
Laguarta said PepsiCo is planning cost reductions aimed at cutting redundancies and discretionary spending to help fund investments in innovation and marketing. A separate Seeking Alpha report noted the company plans additional investment in innovation, brand building, sharper execution and cost reduction initiatives specifically in North America. On the product side, PepsiCo's snacks strategy has leaned into simpler ingredients, "alternative" oils and functional benefits like protein and fiber, while its drinks business remains focused on functional hydration, flavored soft drinks, energy drinks and zero-sugar options, per CNBC.
Shares little changed
Shares of PepsiCo fell less than 1% in premarket trading following the report, CNBC reported. CNBC also said Laguarta was scheduled to join its broadcast at 10 a.m. ET to discuss the results.
Bottom Line
PepsiCo's third quarter underscored a familiar pattern this year: international units, particularly Latin America Foods and Asia Pacific, are carrying growth, while North American beverages and snacks continue to underperform management's own expectations, with Laguarta calling the home market a "meaningful opportunity for improvement" and CFO Steve Schmitt describing the domestic turnaround as slower than expected. Interpreting those disclosures, the raised full-year revenue outlook of about 6% appears to reflect that international strength, while the trimmed core EPS growth target of 2.5% to 3.5% aligns with CNBC's reporting that the company lowered its earnings forecast as home-market struggles weigh on profits with one quarter left in 2026. PepsiCo has not quantified the profit impact of its planned North American investments, so the relative weight of each factor on full-year earnings is not disclosed in the materials reviewed.
DISCLAIMER: Traders Agency does not offer financial advice. The information provided is for educational purposes only and should not be considered financial advice. Traders Agency is not responsible for any financial losses or consequences resulting from the use of the information provided. Trading carries inherent risks and may not be suitable for all individuals. You are advised to conduct your own research and seek personalized advice before making any investment decisions, recognizing the potential risks and rewards involved.
- Seeking Alpha Market News: PepsiCo in Charts: LatAm Foods & Asia Pacific continue to fuel global momentum in Q3 · accessed Oct 8, 2026
- Seeking Alpha Market News: PepsiCo sees stronger results globally than in North America · accessed Oct 8, 2026
- CNBC Top News: PepsiCo (PEP) Q3 2026 earnings · accessed Oct 8, 2026
- Seeking Alpha Market News: Earnings Snapshot:PepsiCo beats Q3 estimates, raises revenue outlook,trims core EPS growth · accessed Oct 8, 2026
- Seeking Alpha Market News: PepsiCo beats top-line and bottom-line estimates; updates FY26 outlook · accessed Oct 8, 2026
- PepsiCo, Inc.: https://investors.pepsico.com/docs/pepsico-5v9wci20/media/Files/investors/q3-2026-earnings-release.pdf · accessed Oct 8, 2026
See more from Traders Agency on Google
Make us a preferred source and our market analysis will appear more prominently in your Google Search, Top Stories, and AI results.
Add to Preferred Sources