The Fed's interest rate mistake wasn't raising rates last month. The mistake is what happens next if it refuses to admit the damage already done.
Wall Street is betting on more hikes. The data says the opposite is coming, and faster than anyone on CNBC is willing to say out loud.
Last month, the Federal Reserve raised interest rates for the first time in three years. The 10-year Treasury yield has pushed above 5%, the highest level since 2007. The 30-year hit a level we haven't seen since 2002. Mortgage rates are back above 7%. And in September, Regions and Bank of America both fell about 10%.
That's not a coincidence. Something is starting to crack, and we get proof of it on October 14th when Bank of America reports earnings.
If you have money sitting in a savings account right now, this matters to you directly.
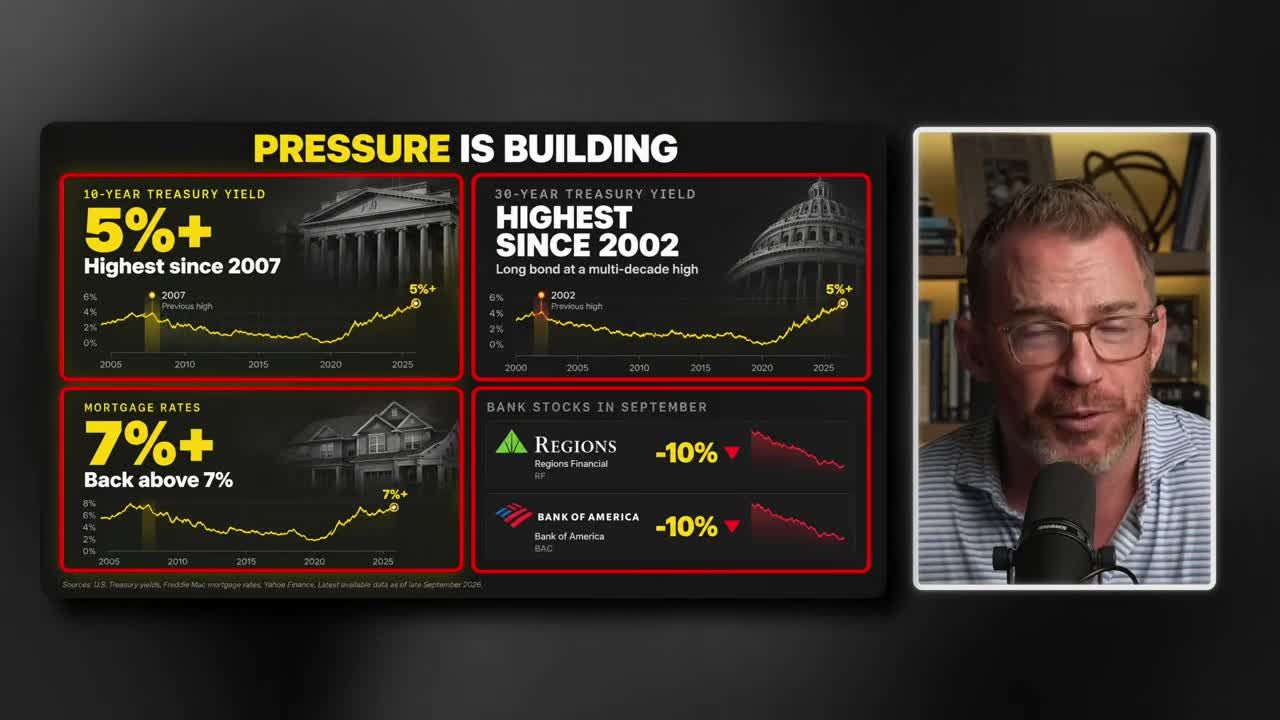
Why Did the Fed Hike Again?
Bottom Line: The fed's interest rate mistake is not the September hike itself but the risk of staying locked into more hikes while bond losses and funding costs quietly pile up at banks and the Treasury. If that pressure keeps building, the Fed may be forced to reverse course faster than Wall Street currently expects.
The September 16th decision set off a chain reaction
The Fed raised its benchmark rate on September 16th, pushing the rate it pays banks on reserves up to 3.9%. Wall Street read that as the start of a new hiking cycle and is pricing in more increases ahead.
But raising rates isn't free. Every hike makes existing bonds held by banks worth less, increases what the Fed itself pays out, and piles billions in new interest costs onto a federal government that's already drowning in debt.
The next Federal Reserve meeting, October 28th, will tell us whether the central bank realizes it.
What Is the Fed's Interest Rate Mistake?
It's simple: the Fed is hiking into a banking system already sitting on massive unrealized bond losses, while a federal government buried in debt watches its interest bill explode. Every additional hike makes both problems worse, not better.
Here's the mechanic most people miss. A bank takes your deposit, pays you a little interest, then lends that money out or buys bonds at a higher rate and pockets the spread. That works fine until rates rise.
When rates rise, the bonds a bank already owns lose value. If you're holding a bond paying 2% and the government starts issuing new ones paying 5%, nobody wants your old bond unless you sell it at a steep discount.
The SVB Blueprint
That's exactly what killed Silicon Valley Bank in 2023. During COVID, deposits poured in while rates sat near zero, so SVB parked that money in long-term bonds for a slightly better yield. Then the Fed started hiking.
By the end of 2022, SVB's bond portfolio was sitting on roughly $15 billion in losses against an equity cushion of only about $16 billion. When SVB sold some of those bonds to cover withdrawals, it locked in the loss. Word got out, customers pulled $42 billion in a single day, and the bank failed the next day.
That problem never actually went away. It just got quieter.
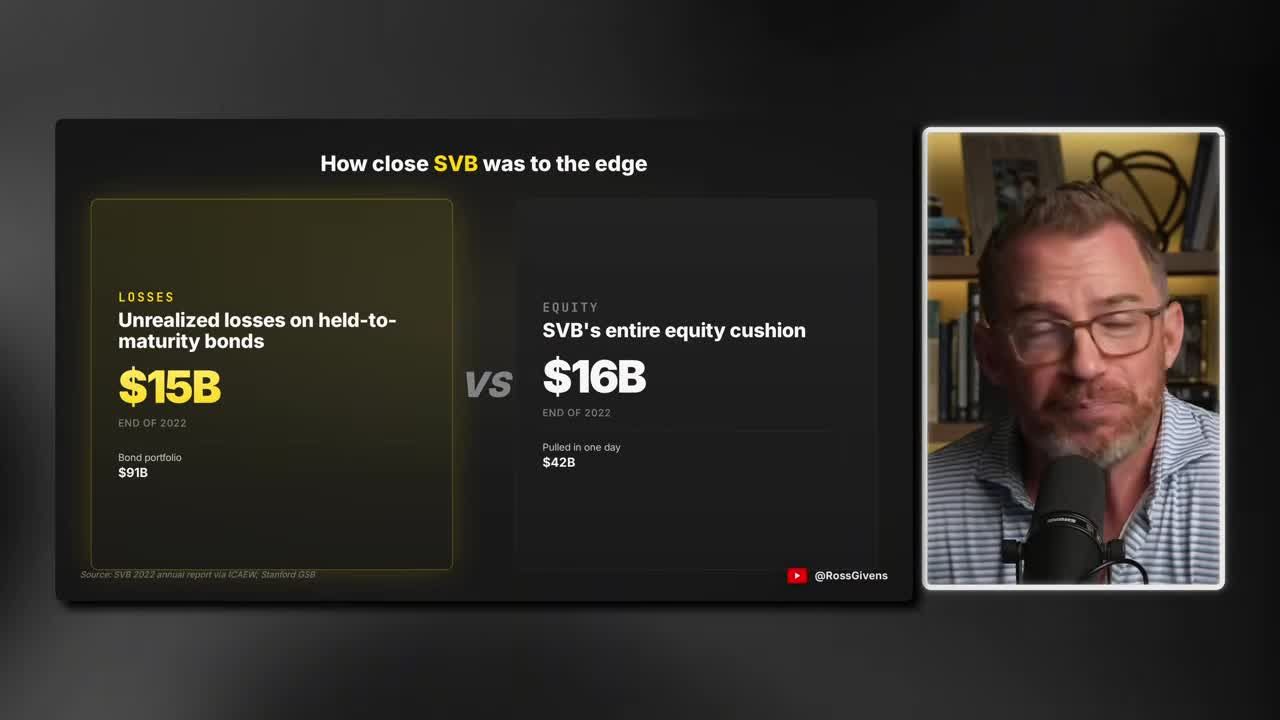
How Are Rising Rates Affecting Bank Balance Sheets?
The Fed's interest rate mistake shows up first on bank balance sheets. Bank of America is holding $56 billion in bonds labeled "held to maturity," a cute label that lets a bank avoid marking losses down on its balance sheet as long as it never sells. As of June 30th, those bonds were already underwater by $82 billion.
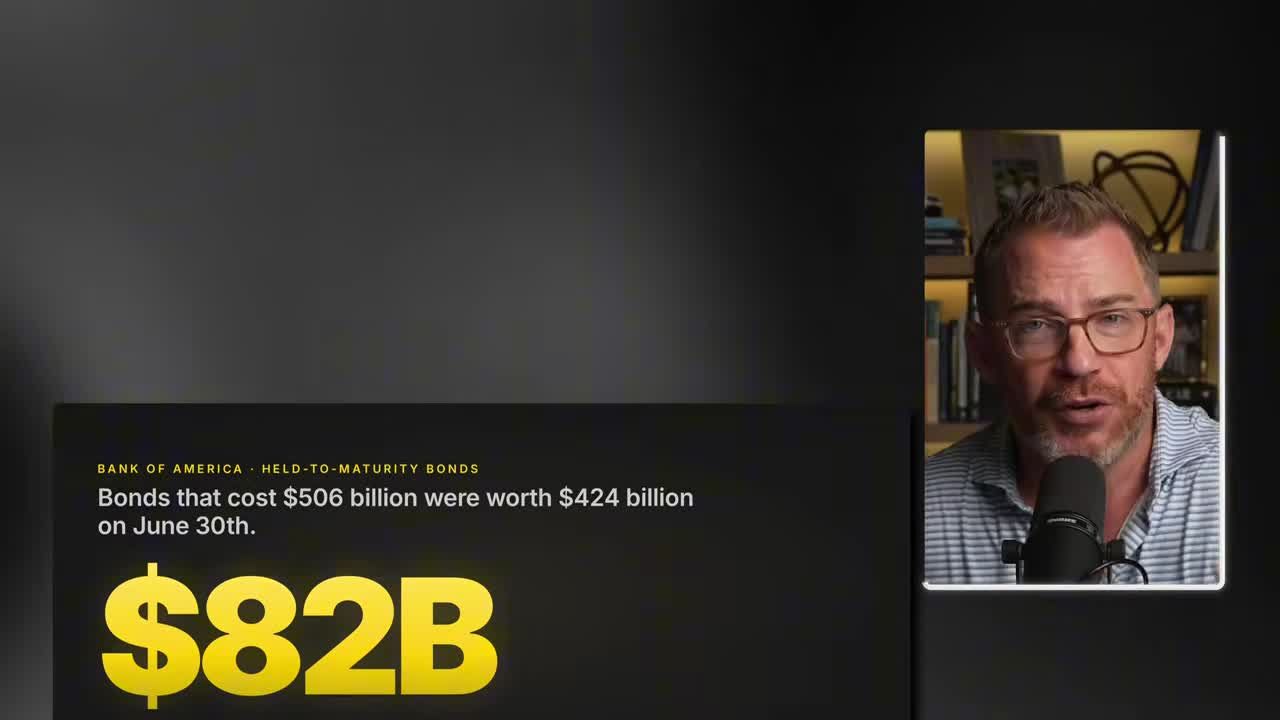
To be fair, Bank of America is not Silicon Valley Bank. That $82 billion represents about 40% of its tangible equity, not all of it, and nearly half its deposits come from everyday consumer accounts rather than big tech startup money.
But the June 30th number was measured when the 10-year yield sat at 4.45%. It's above 5% now, and every tick higher makes those bonds worth even less.
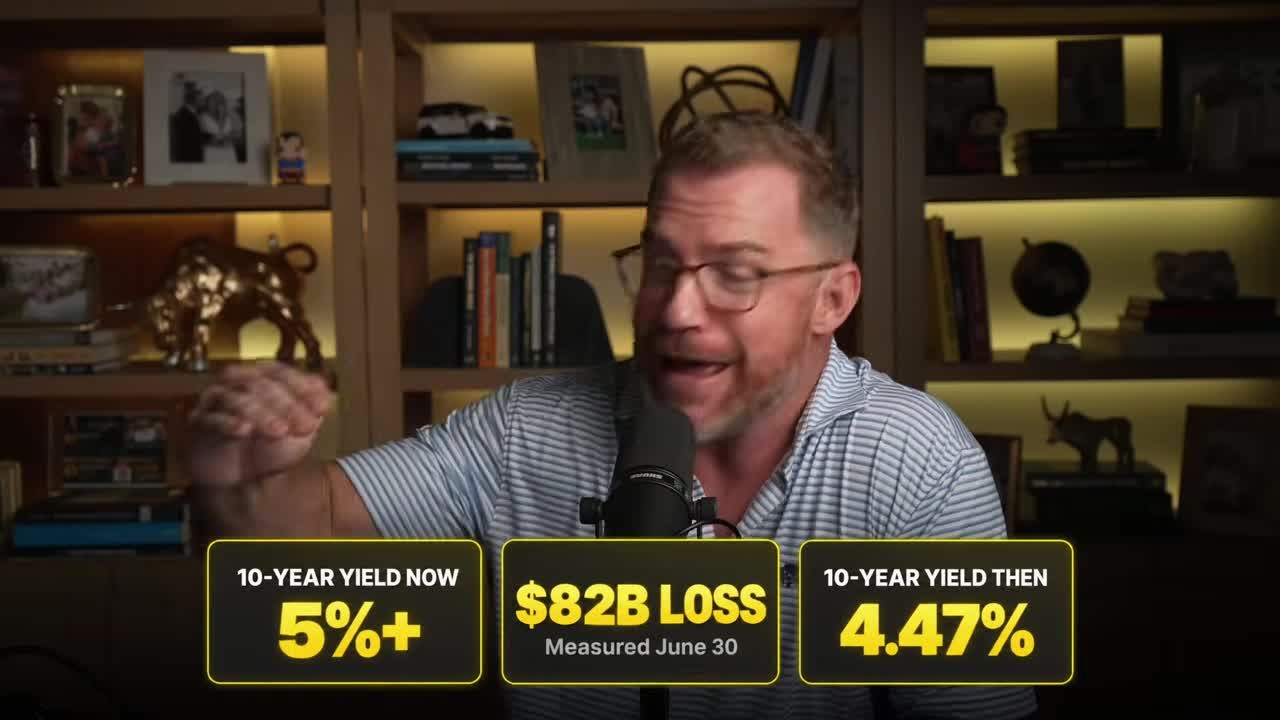
The Second Problem Is Your Savings Account
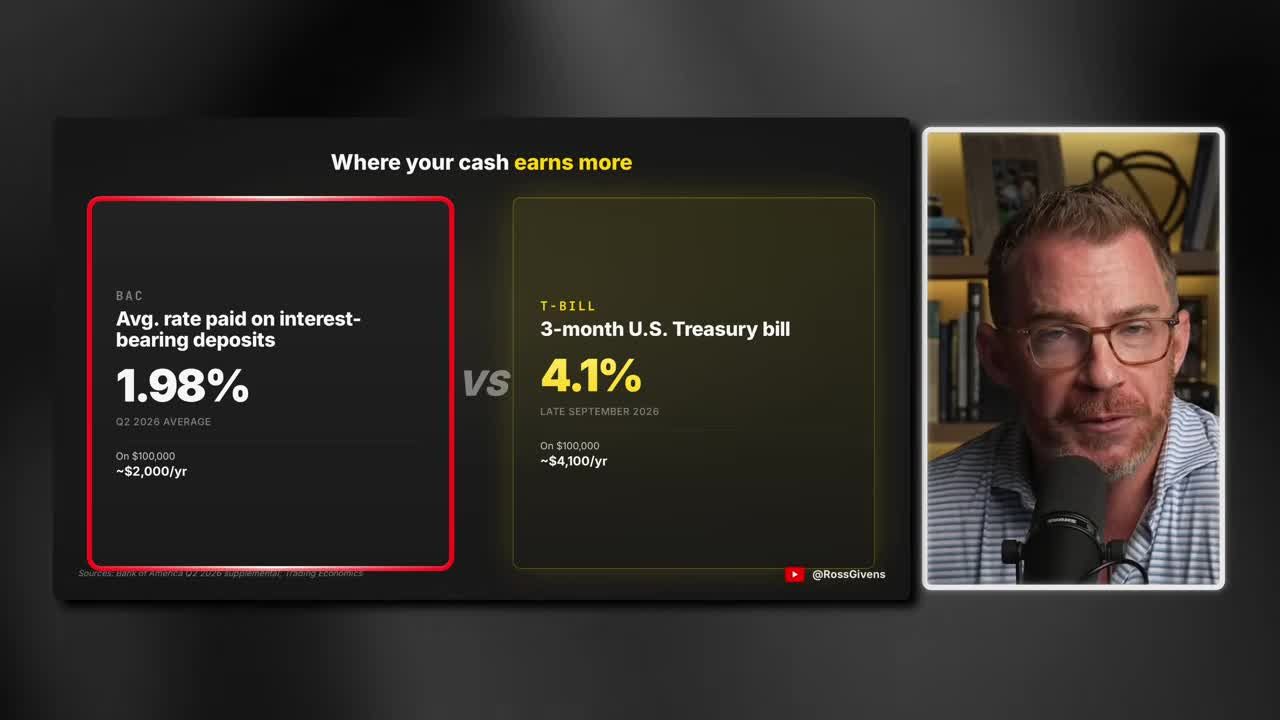
In the second quarter, Bank of America paid an average of just under 2% on interest-bearing deposits. A simple 3-month Treasury bill or money market account pays about 4%.
On a $100,000 deposit, that's the difference between earning a little less than two grand a year and earning just over four grand. When the gap gets that wide, money starts moving. It always does.
When deposits leave, a bank has exactly two choices:
- Pay depositors more to keep them, which crushes profits
- Sell bonds to cover the withdrawals, which turns paper losses into real ones
That second option is the SVB playbook, and the stock market is already sniffing it out.
Get an entire year of live weekly mentoring sessions, my newsletter, indicators, bonus reports, tons more. Click the link and I'll see you in the next live session.
Join my Black Ops Trading ClubThe Most Underwater Bank in America
It isn't a commercial bank at all
Bank of America is the clearest example, sitting on $82 billion in unrealized bond losses as of June 30th, with that number likely closer to $100 billion today. But the single most underwater "bank" in the country is the Federal Reserve itself.
The Fed owns trillions of dollars in Treasury and mortgage bonds, most of it bought during COVID when rates sat near zero. All that money printing that caused the inflation? This is where it went. The Fed has the exact same problem as every commercial bank, just at a much bigger scale.
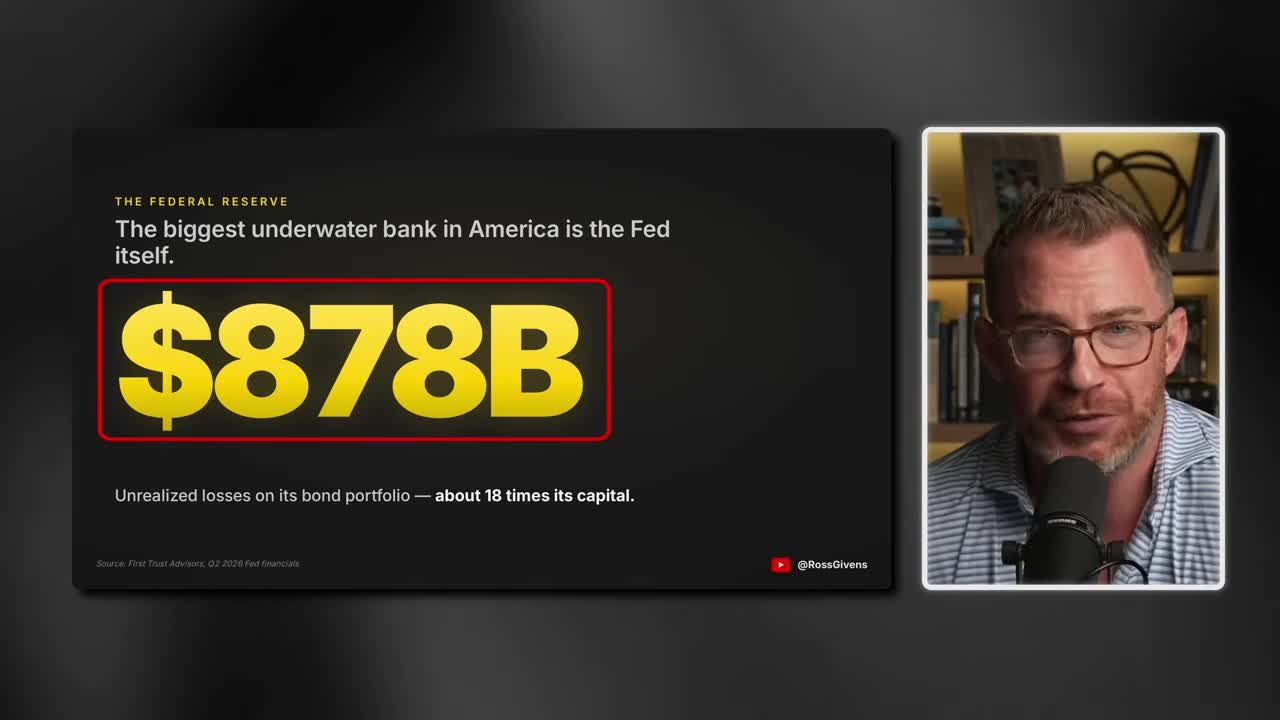
As of the second quarter, the Fed was sitting on $878 billion in unrealized losses, about 18 times its capital.
The Fed can't go bankrupt. It prints the money, and no regulator can shut it down. But it does have a real cash flow problem.
The Fed pays banks interest on reserves parked with it, and that rate is set by the same fed funds rate announced every six or seven weeks. The September 16th hike pushed that payment to 3.9%. Every hike means more money flowing out of the Fed's own accounts.
Why Is Rising Government Debt a Bigger Problem Than Bank Losses?
The Congressional Budget Office projected the US government would spend more than $1 trillion on interest in the fiscal year that just ended. That's more than we spend on national defense, and it eats about 19 cents of every tax dollar collected.
That projection was built using economic conditions from last December. Since then, rates have climbed hard. The 2-year Treasury yield is up more than a full point over the last 12 months.
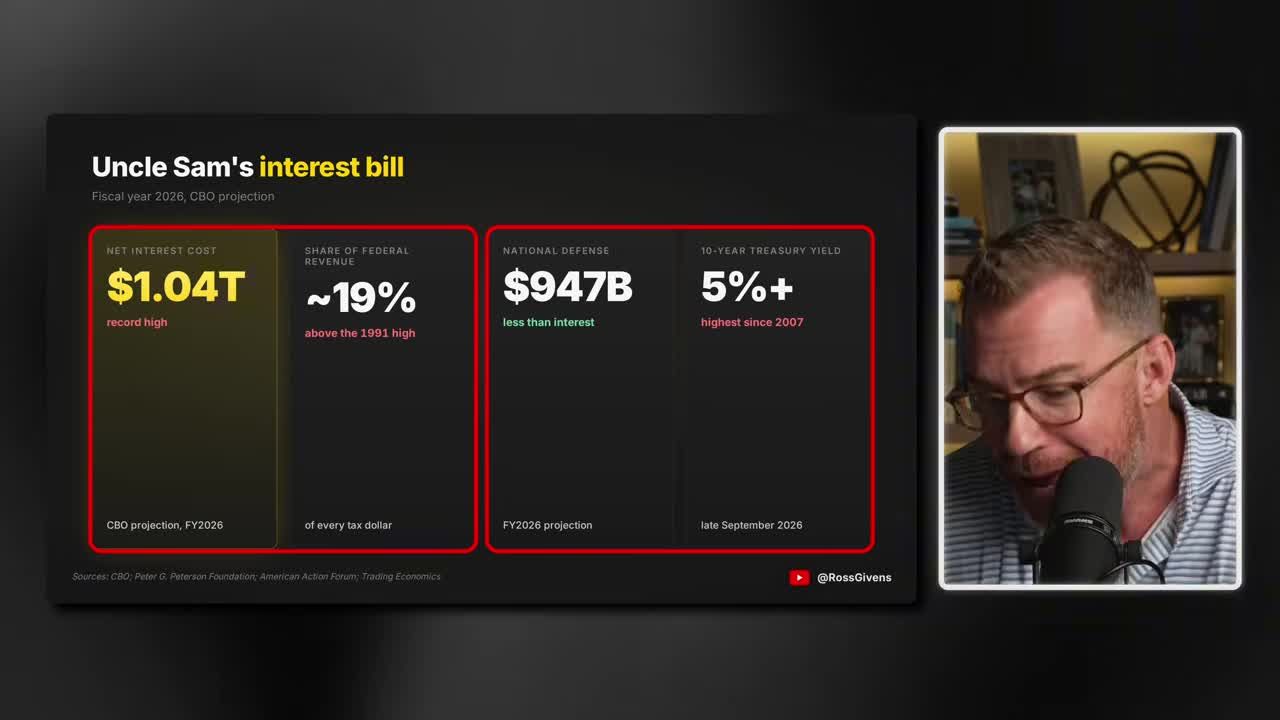
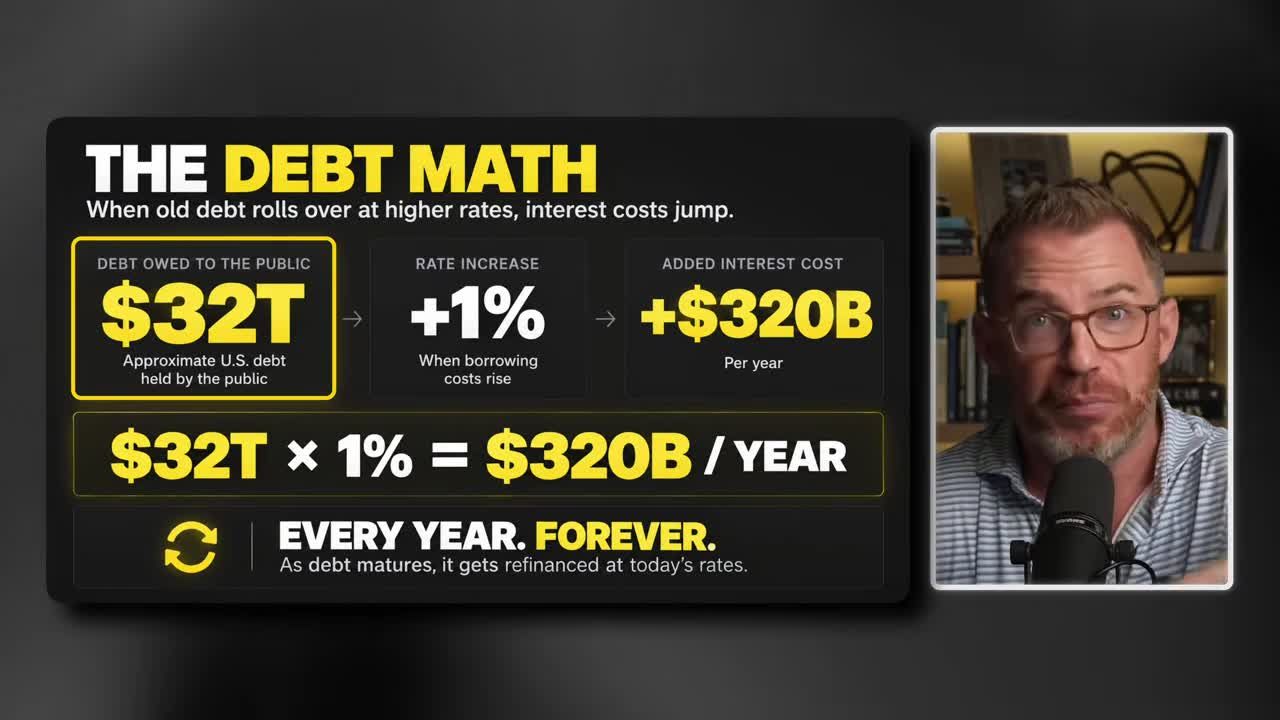
Here's why it compounds so fast. The government owes about $32 trillion to the public. When that debt comes due, it gets rolled into new debt at today's rates.
Every 1% increase in rates adds $320 billion a year in interest. Every year. Forever.
And where does that money come from? More borrowing, which pushes rates higher, which means more interest, which means more borrowing. It snowballs, and the Fed is the only entity that can stop it from spinning out of control.
The Trap the Fed Built
If the Fed keeps hiking, it breaks the banks, breaks its own budget, and blows an ever-growing hole in the federal government's budget. It also kills the housing market, the job market, and just about every bit of GDP growth outside of data centers.
If the Fed stops or cuts, it's doing so with inflation still at 3.4% and oil near $100 a barrel, risking inflation running hotter for years.
Neither choice is good. Only one of them is survivable.
They'll dress it up as "insurance" or "supporting financial stability." They'll cite some nonsensical metric like trimmed median PCE to build a narrative that inflation isn't as bad as we think. Watch for that exact language.
The market is already seeing it. Just two weeks after the September hike, the odds of another hike in October had already dropped to 39%. The New York Fed president has said there's no rush to raise rates again.
The Fed doesn't even need to formally cut on October 28th. It just has to blink. A split vote, an off-hand remark about cooling inflation, a pause at the right moment in a Fed speech. Markets will read any of that as a reversal, and bonds will soar while yields collapse.
What To Do With Your Cash
If your savings are sitting at a big bank earning half a percent, 1%, or even 2%, you don't have to accept that. Treasury bills are paying around 4%. Treasury money market funds pay 4.05% to 4.1%.
And if you keep cash at a bank, remember FDIC insurance only covers up to $250,000. You want to stay under that anyway.
Notes, bills, and money market funds may sound complicated. They're not.
- Call your bank. Ask if they offer a money market fund and what it pays.
- If the answer is garbage or you get the runaround, call another bank and open an account there.
- For Treasury bills, one ticker does it in any brokerage account: SGOV, the zero to three month Treasury bond ETF. Buy $100 or a million, collect a cash dividend every month, buy or sell any time with no restrictions.
How To Position Before the Pivot
1. Stay Away From the Long End
When the Fed is forced to cut, short-term rates fall fast. Long-term rates may not follow. If the market decides the Fed is cutting to bail out the government rather than because it beat inflation, long-term yields could sit still or even rise.
Our government is bankrupt. Let's not sugarcoat it. Why would you lend money to a bankrupt borrower for 10, 20, or 30 years? Nothing would make me buy a long-term Treasury bond today.
2. The Trade Is the 2-Year Note
The 2-year currently pays close to 5% a year. You can buy it straight from a brokerage account, or through the ETF ticker SHY, which holds Treasuries maturing between one and three years.
When the Fed cuts, the 2-year yield falls first and falls fastest. As yields fall, the price of that note rises. Roughly speaking, every 1% drop in the 2-year yield adds about 2% to the note's price.
If the Fed cuts a full percentage point over the next year, that's the 5% interest plus a 2% price gain. Call it 7% total, on a government bond. If I'm wrong and the Fed keeps hiking, the price dips slightly, but you still collect your 5%, and you get every dollar back if you hold to maturity. There's risk, but not much.
Wall Street has a fancy name for this setup: a "bull steepener." You'll hear it from guys on CNBC in elbow-patch blazers because it makes them feel elite. All it means is short-term rates falling faster than long-term rates. The 2-year is where you want to be for that, not the 30-year.
3. Lean Into Hard Assets
A rescue like this gets paid for with a weaker dollar. Gold is already above $4,000 an ounce, and I think it goes exponentially higher in the coming years.
Hard assets across the board, gold, commodities, and high quality stocks with real cash flow, are the assets likely to win over the long term as the dollar loses.
Two Dates To Mark
- October 13th and 14th: Wells Fargo and Bank of America report earnings. If bond losses jumped or deposits are rushing out the door, pressure on the Fed gets a lot bigger.
- October 28th: The next Fed meeting. No formal cut required. A shift in language is enough for markets to react.
The Fed Isn't in Charge, the Math Is
Wall Street keeps acting like the Fed is calling the shots. It isn't. The Fed's interest rate mistake was hiking into a banking system already sitting on billions in unrealized losses and a federal government whose interest bill is growing faster than its revenue can keep up with.
The math says the Fed has to cut, whether it wants to admit that or not.
Every point higher in rates adds $320 billion a year in permanent interest costs to a government already spending more on interest than on defense. Every point higher pushes more banks toward the SVB playbook. This doesn't need a crisis headline to build. It's building in the bond math every single day rates stay elevated.
Watch the earnings on October 13th and 14th. Watch the language coming out of the October 28th meeting. In the meantime, get your cash earning a real rate, stay away from long-dated bonds, and position where the math actually favors you.
Get an entire year of live weekly mentoring sessions, my newsletter, indicators, bonus reports, tons more. Click the link and I'll see you in the next live session.
DISCLAIMER: Traders Agency does not offer financial advice. The information provided is for educational purposes only and should not be considered financial advice. Traders Agency is not responsible for any financial losses or consequences resulting from the use of the information provided. Trading carries inherent risks and may not be suitable for all individuals. You are advised to conduct your own research and seek personalized advice before making any investment decisions, recognizing the potential risks and rewards involved.
See more from Traders Agency on Google
Make us a preferred source and our market analysis will appear more prominently in your Google Search, Top Stories, and AI results.
Add to Preferred Sources