Procter & Gamble raised its fiscal 2027 all-in sales growth outlook to a range of 2% to 4%, up from 1% to 3%, after reporting first-quarter net sales and core earnings per share that topped Wall Street estimates. The company said the higher range reflects its acquisition of supplements brand Thorne as of October 1, 2026, according to P&G's investor relations release. At the same time, P&G disclosed a larger expected drag from commodities, tariffs and freight, with the estimated after-tax cost headwind for the fiscal year rising to $0.79 per share.
Quarter beats consensus
For the three months ended September 30, 2026, P&G reported net sales of $23.3 billion, up 4% from a year earlier, and core earnings per share of $2.00, versus $1.99 in the prior-year quarter. According to CNBC, citing an LSEG survey of analysts, Wall Street had expected $1.88 in adjusted earnings per share and $22.8 billion of revenue, putting the reported results $0.12 above the EPS estimate (2.00 minus 1.88) and $0.5 billion above the revenue estimate (23.3 minus 22.8). An Investing.com report carried by Yahoo Finance cited a slightly different consensus, $1.89 per share and $22.82 billion in sales, which would put the earnings beat at $0.11.
Operating income rose 1% to $5.937 billion, but operating margin fell 70 basis points to 25.5%, and net earnings dipped to $4.757 billion from $4.781 billion a year earlier, per figures reported by TradingView. Shares rose more than 2% in premarket trading following the release, according to both CNBC and Yahoo Finance.
Guidance raised on Thorne, organic range held steady
P&G kept its organic sales growth guidance, which excludes the impacts of foreign exchange and acquisitions and divestitures, unchanged at 1% to 3% for fiscal 2027, even as it lifted the all-in sales range to 2% to 4% to account for Thorne. The company also now expects a core effective tax rate of 20% to 21% for the fiscal year, according to the investor relations release, compared with the approximately 20% rate it had projected in its fiscal 2026 fourth-quarter release. Core EPS guidance of $6.89 to $7.11 was maintained, a range that the Investing.com report carried by Yahoo Finance noted sits below the $7.39 per share analysts expect for the fiscal year.
Cost headwinds climb
An earnings review from finsee.ai detailed how the components of P&G's cost outlook shifted since July. The site reported that P&G now estimates full-year after-tax cost headwinds of $0.79 per share, an 11% drag on core EPS, up from the $0.56 per share, or 8% drag, it had projected three months earlier. That is a $0.23 increase, or roughly 41% (calculated as 0.79 minus 0.56, divided by 0.56), by our calculation based on the two disclosed figures.
Within that total, finsee.ai reported that after-tax commodity, energy and freight costs are now expected to run about $1.4 billion, up from roughly $1.0 billion three months ago, a $0.4 billion increase, or 40% (1.4 minus 1.0, divided by 1.0), again by our calculation. The site also reported that higher net interest expense is now expected to cost $300 million after tax, double the $150 million estimated previously, a 100% increase by the same type of calculation.
Volume-led growth, uneven across segments
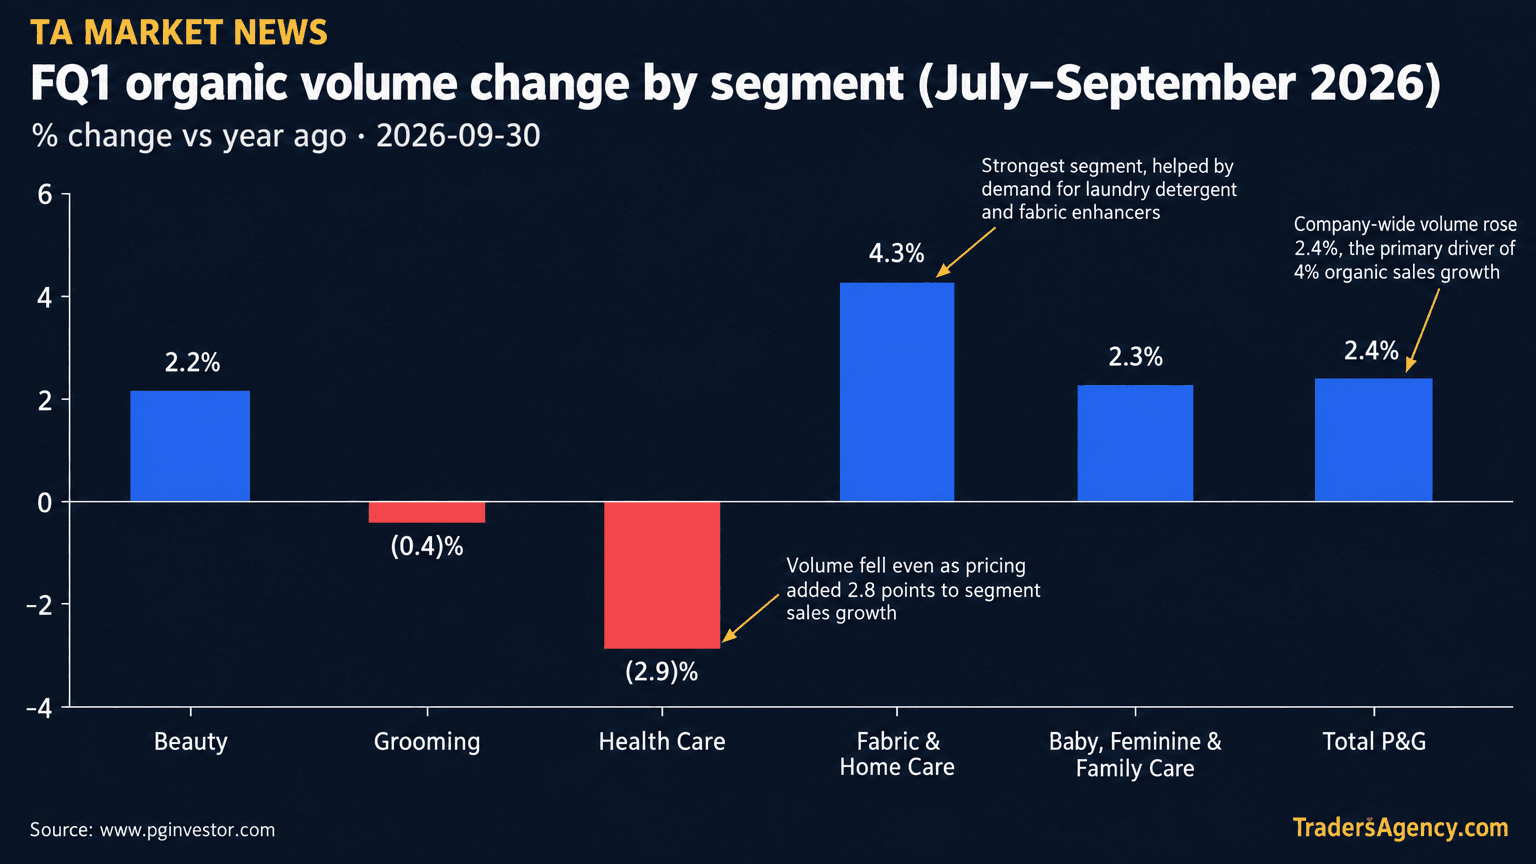
Total company organic sales grew 4% in the quarter, driven by a 2.4% increase in organic volume, a 1.1% favorable mix impact and a 0.4% pricing contribution, per the investor relations release. CNBC called the 2.4% volume increase a strong start to the new fiscal year, noting that in fiscal 2026 P&G reported just one quarter of volume growth.
Segment results were mixed. Fabric & Home Care, which includes Tide and Febreze, posted the strongest organic volume gain at 4.3%, which CNBC attributed to stronger demand for laundry detergent and fabric enhancers. Health Care volume fell 2.9% even as pricing added 2.8 points to that segment's sales growth, and Grooming volume declined 0.4% while pricing there contributed 3.5 points. By region, the investor relations release said Baby Care organic sales grew on volume gains concentrated in Greater China and North America, partly offset by lower pricing primarily in North America, while Personal Care organic sales grew on volume gains in Greater China and Europe. The release did not disclose regional sales totals, a gap also flagged by finsee.ai's review.
Management commentary
P&G returned $3.9 billion to shareholders in the quarter through $2.6 billion in dividends and $1.3 billion in buybacks, and still expects to pay more than $10 billion in dividends and repurchase about $5 billion of shares for the full fiscal year, Yahoo Finance reported. Operating cash flow was $5.8 billion, with free cash flow productivity of 93%, per the investor relations release.
Chief Executive Shailesh Jejurikar said in the investor relations release: "While we expect there will continue to be geopolitical and economic challenges, this strong start keeps us on track to deliver within our guidance ranges for organic sales growth, core EPS growth and free cash flow productivity for the fiscal year." On the earnings call, Chief Financial Officer Andre Schulten described a bifurcated consumer and an "intense" competitive environment, telling analysts, per CNBC, "we will price, and we will price with innovation, not jeopardizing the topline momentum." One qualification for investors weighing the guidance: finsee.ai's review argued that holding the full-year organic range at 1% to 3% after a 4.0% first quarter implies organic growth of only about 1.3% over the remaining three quarters at the 2.0% mid-point — an interpretation drawn from the disclosed guidance range and reported quarterly growth rate, not a company forecast.
DISCLAIMER: Traders Agency does not offer financial advice. The information provided is for educational purposes only and should not be considered financial advice. Traders Agency is not responsible for any financial losses or consequences resulting from the use of the information provided. Trading carries inherent risks and may not be suitable for all individuals. You are advised to conduct your own research and seek personalized advice before making any investment decisions, recognizing the potential risks and rewards involved.
- CNBC Top News: Procter & Gamble (PG) Q1 2027 earnings · accessed Oct 22, 2026
- www.pginvestor.com: P&G Announces Fiscal Year 2027 First Quarter Results · accessed Oct 22, 2026
- markets.ft.com: P&G Announces Fiscal Year 2027 First Quarter Results · accessed Oct 22, 2026
- finsee.ai: The Procter & Gamble Company Q1 2027 Earnings Review · accessed Oct 22, 2026
- finance.yahoo.com: Procter & Gamble shares rise 2% in premarket trade after Q1 sales, profit beat · accessed Oct 22, 2026
- www.tradingview.com: Procter & Gamble Posts 4% Sales Growth; Core EPS Rises to $2.00 · accessed Oct 22, 2026
- www.cnbc.com: Procter & Gamble (PG) Q1 2027 earnings · accessed Oct 22, 2026
- www.youtube.com: - YouTube · accessed Oct 22, 2026
- The Procter & Gamble Company: P&G Announces Fourth Quarter and Fiscal Year 2026 Results · accessed Oct 22, 2026
- us.pg.com: Procter & Gamble · accessed Oct 22, 2026
See more from Traders Agency on Google
Make us a preferred source and our market analysis will appear more prominently in your Google Search, Top Stories, and AI results.
Add to Preferred Sources