Starbucks reported U.S. comparable coffeehouse sales growth of 7.7% in its fiscal fourth quarter, ahead of Wall Street expectations, even as a sharp drop in international revenue tied to the restructuring of its China business pulled overall company sales lower. The split results, reported in the company's fiscal 2026 fourth-quarter release, illustrate a turnaround effort that is gaining traction domestically while the China licensed joint-venture conversion reshapes how international revenue shows up on the income statement, according to Starbucks' earnings release and CNBC.
U.S. Comparable Sales Beat Estimates
U.S. comparable coffeehouse sales rose 7.7% in the quarter, driven by a 5.2% increase in average ticket and a 2.4% increase in transactions, according to Starbucks' earnings release. CNBC reported that the figure topped StreetAccount's consensus estimate of 6.5% growth. Globally, comparable sales increased 7.2%, also beating the roughly 6% analysts had expected, CNBC said.
Outside North America, the picture was weaker. International comparable sales rose just 0.9%, as a 3.7% increase in average ticket was partially offset by a 2.8% decline in comparable transactions, per the earnings release. CNBC reported that the figure fell short of analyst estimates of a 3.2% increase, according to StreetAccount, with traffic declines offsetting ticket growth.
China Conversion Drives International Revenue Decline
The gap between modest international comparable-sales growth and a much steeper drop in reported international revenue reflects a structural change rather than a pure demand signal. Starbucks said net revenues for its International segment fell 37% year over year to $1.3 billion in the quarter, which the company attributed primarily to the conversion of its China retail operations to a licensed joint-venture model in the third quarter of fiscal 2026, according to the earnings release.
That distinction matters for how investors read the quarter. International comparable sales, which measure like-for-like performance at existing stores, were still positive at 0.9%, suggesting underlying demand outside North America was soft but not collapsing. The much larger 37% revenue decline, by contrast, was attributed by the company primarily to the conversion of its China retail operations to a licensed joint-venture model in the third quarter of fiscal 2026. Interpreted against that company attribution, the revenue-line drop appears to reflect substantially a change in how China operations are reported under the new structure rather than a broad deterioration in international demand, though the 2.8% decline in international comparable transactions indicates some genuine traffic softness persists alongside the structural shift.
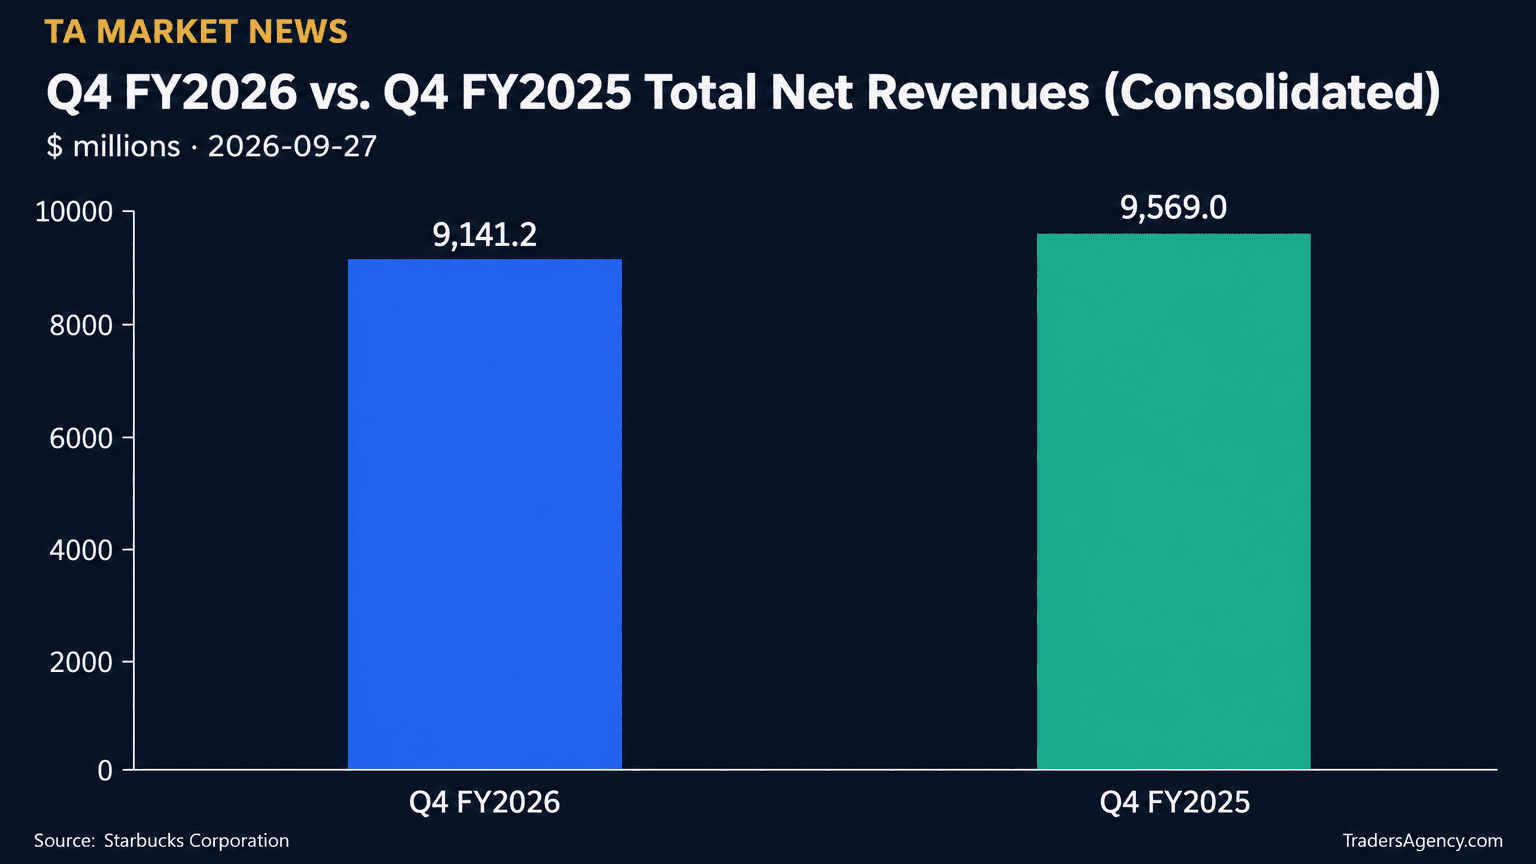
At the consolidated level, Starbucks reported total net revenues of $9,141.2 million in the quarter, down from $9,569.0 million a year earlier. By our calculation, that is a decline of $427.8 million, or roughly 4.5% ($9,141.2 million minus $9,569.0 million, divided by $9,569.0 million). Seeking Alpha framed the quarter as a revenue miss that was overshadowed by solid underlying results and upbeat profit guidance.
What's Fueling the U.S. Turnaround
Management credited the U.S. momentum to its "Back to Starbucks" strategy, which has centered on improving service, making cafes more welcoming and sharpening marketing, according to CNBC. CEO Brian Niccol told analysts that "Starbucks brand affinity is at near record levels as our menu innovation, marketing and merchandise continue to create moments that drive culture and bring people into our coffee houses," CNBC reported.
Specific initiatives cited by the company include the North American fall menu rollout, featuring the pumpkin spice latte, which Starbucks said was its strongest-ever autumn launch day, and matcha, which has grown into a $1 billion drink for the company, per CNBC's reporting. Starbucks also completed more than 1,700 cafe "uplifts" across the U.S. and Canada by fiscal year-end, aimed at making stores more welcoming through changes like added seating and softer lighting. The company has said locations receiving such makeovers see higher transactions afterward, CNBC noted.
As part of the same turnaround push, Starbucks closed approximately 250 underperforming company-operated North America coffeehouses in September 2026, representing about 1% of its North American footprint, according to both CNBC and the company's earnings release.
Looking Ahead to Fiscal 2027
Niccol said Starbucks enters fiscal 2027 "with momentum, a clear set of priorities and higher ambitions for what Starbucks can become," and told analysts the company is ahead of schedule on the fiscal 2028 targets it laid out at its January investor day, CNBC reported. CFO Cathy Smith said the company's recently increased dividend and plans to resume share repurchases in fiscal 2027 "underscore our confidence and disciplined focus on driving sustainable long-term value," according to the earnings release.
Because the China joint-venture conversion took effect mid-way through fiscal 2026, year-over-year international revenue comparisons are likely to keep reflecting that structural shift until the conversion is fully lapped, which is a mechanical effect of the timing rather than a company forecast of weakening demand. Seeking Alpha's description of Starbucks as "back on the offense" in a follow-up piece points to market attention shifting toward whether U.S. momentum can offset that international reporting drag in the coming fiscal year.
Bottom Line
Starbucks' fiscal fourth quarter showed a business bifurcated between a reinvigorated U.S. cafe experience, where comparable sales of 7.7% topped StreetAccount's 6.5% estimate as reported by CNBC, and an international segment whose reported revenue was reshaped by the China licensed joint-venture conversion. Total net revenue fell 4.5% to $9,141.2 million, while International segment revenue dropped 37% to $1.3 billion, a decline the company attributed primarily to that structural change. Management, meanwhile, says it enters fiscal 2027 with momentum, pointing to continued store investment, a recently increased dividend and plans to resume share repurchases. Investors weighing the quarter will likely need to separate the reporting effect of the China deal from the comparable-sales trends that more directly reflect customer demand.
DISCLAIMER: Traders Agency does not offer financial advice. The information provided is for educational purposes only and should not be considered financial advice. Traders Agency is not responsible for any financial losses or consequences resulting from the use of the information provided. Trading carries inherent risks and may not be suitable for all individuals. You are advised to conduct your own research and seek personalized advice before making any investment decisions, recognizing the potential risks and rewards involved.
- CNBC Top News: Starbucks (SBUX) Q4 2026 earnings · accessed Oct 30, 2026
- Seeking Alpha Market News: Starbucks' revenue miss overshadows solid FQ4 results, upbeat profit guidance · accessed Oct 30, 2026
- Seeking Alpha Market News: Grande expectations: Starbucks back on the offense · accessed Oct 30, 2026
- Starbucks Corporation: 4Q26-Earnings-Release-_2026-10-29_-FINAL.pdf · accessed Oct 30, 2026
- Business Wire via Nasdaq: Starbucks Reports Q4 and Full Fiscal Year 2026 Results · accessed Oct 30, 2026
See more from Traders Agency on Google
Make us a preferred source and our market analysis will appear more prominently in your Google Search, Top Stories, and AI results.
Add to Preferred Sources